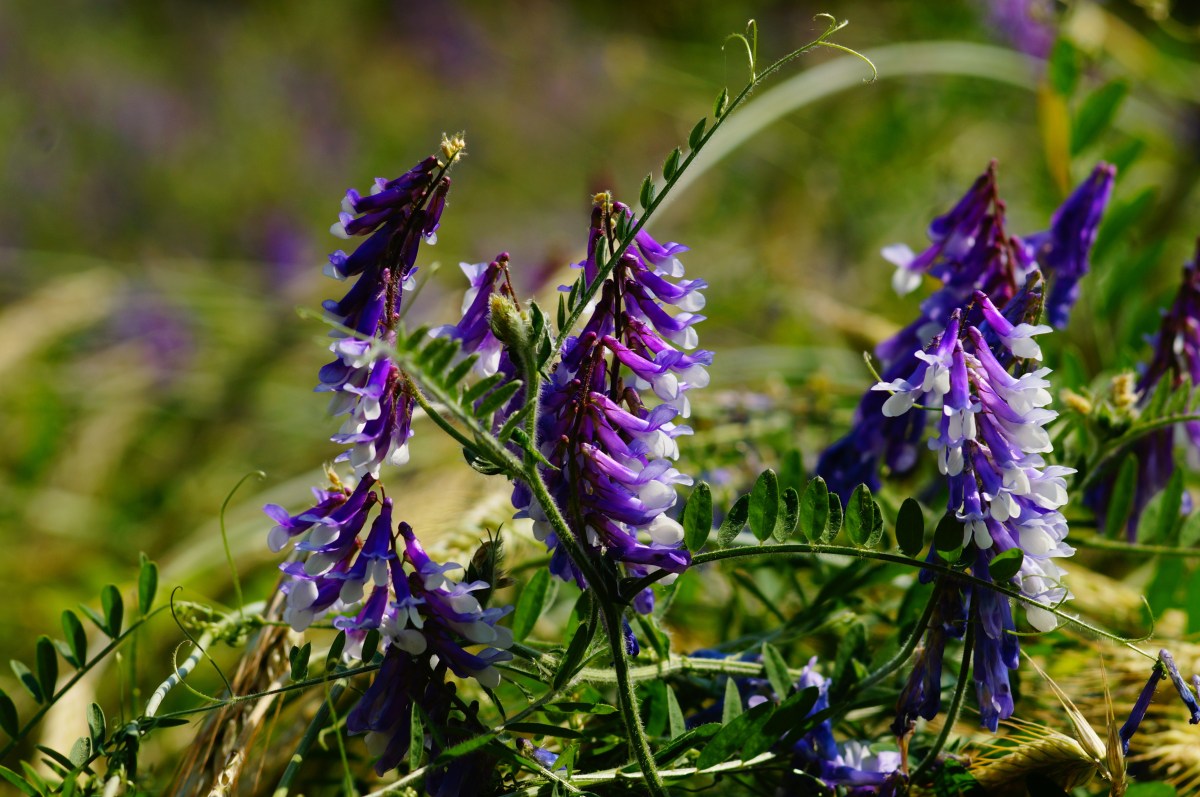
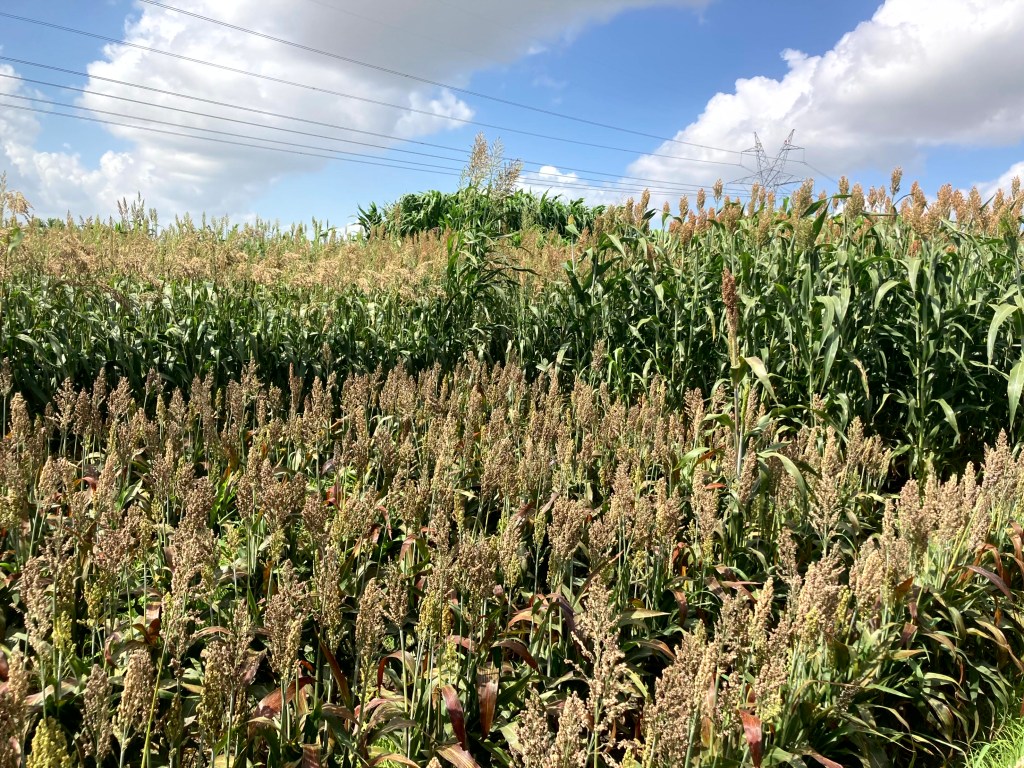
Cereal rye and hairy vetch are two of my favorite winter cover crops for Texas organic farms. Rye suppresses weeds while hairy vetch fixes nitrogen, making them a productive combination for protecting soil and preparing fields for spring planting.
It is fall in Texas, although the weather certainly doesn’t feel very fall-like. Some organic farmers have finished harvest, others are just starting, and some still have a few weeks to go. But we are heading into an El Niño winter weather pattern, with increased chances for wetter conditions across much of Texas. And in some parts of the state, that fall moisture is already arriving. One of my organic cooperators near in the Texas Panhandle just reported 4 (now it is 10) inches of rain on a field where we planted our organic small-grain variety trial on September 17.1
So I have a question for you: Are you planning on a cover crop?
Organic commodity prices are up and supplies are tight. A good winter cover crop can help get you on the right path for spring planting, but we need to get it planted and growing to capture those benefits. When organic growers ask me about winter cover crops for Texas, cereal rye and hairy vetch are usually at the top of my list. They are among our most broadly adapted winter-hardy cover crops, and I like this combination because the two crops do different jobs—and they do those jobs well. Rye provides ground cover, a large fibrous root system, and substantial biomass, while hairy vetch adds a legume capable of supplying biologically fixed nitrogen to the cropping system.
Rye: Put Something in the Field Before the Weeds Get There
Cereal rye is one of our best tools for winter weed suppression. It establishes well under cool conditions, competes strongly for light, water, and nutrients, and can produce enough biomass to physically suppress winter and early spring weeds. Rye also produces natural compounds that can inhibit germination and early growth of some weed species—a process called allelopathy.2
For an organic farmer who cannot simply reach for a postemergence herbicide, that combination of competition, residue, and allelopathy can be extremely valuable. I like to think of it this way: the goal is not simply to grow a cover crop; it is to occupy the space that weeds would otherwise use. Every square foot occupied by vigorous rye is a square foot where a winter weed has a harder time getting established.
Hairy Vetch: Grow Some of Your Own Nitrogen
Hairy vetch brings nitrogen into the system. Working with nitrogen-fixing bacteria in root nodules, vetch captures nitrogen from the atmosphere and converts it into organic forms. As the vetch residue decomposes following termination, a portion of that nitrogen can become available to the following crop.
How much nitrogen we actually gain depends on stand establishment, biomass production, planting date, soil conditions, effective nodulation, and when the vetch is terminated. I do not treat vetch nitrogen as a guaranteed fertilizer rate. However, a good stand producing substantial spring biomass can make a meaningful contribution to the nitrogen budget of the following crop.
Vetches and rye as a mixed crop is a classic cultivation method that is popular again, especially in organic farming.
Why I Like Rye and Vetch Together
What I especially like is the way rye and vetch complement each other. Rye gives us biomass, weed competition, soil protection, and an extensive fibrous root system. Vetch gives us nitrogen fixation and residue with a lower carbon-to-nitrogen ratio that generally decomposes more readily.
Put them together and we have a more balanced cover crop than either species alone. For Texas organic production, where we are trying to manage weeds, protect the soil, encourage biological activity, and supply nutrients without synthetic fertilizers, cereal rye and hairy vetch are difficult to beat as a winter combination.
Remember the Crop That Comes Next
The key is remembering that the cover crop is part of the crop rotation, not simply something we plant between cash crops. Planting date, seeding rate, termination timing, available soil moisture, and the needs of the following crop all matter.
That last point is especially important in Texas. I want enough spring growth to capture the benefits of the rye and vetch, but I do not want my cover crop using water that I will desperately need to establish cotton, corn, sorghum, peanuts, or another summer crop. In our drier production regions, termination timing can be just as important as how much biomass we produce.
So as harvest moves along this fall, take a look at those fields and ask yourself:
What do I want growing there this winter—rye and vetch, or weeds?
For many Texas organic farms, I know which one I would choose.
Rising commercial fertilizer prices could increase competition for manure, compost, and other organic fertility inputs. Organic farmers may want to contact suppliers now and begin securing the nutrients they will need for the 2027 crop.
Harvest is underway or approaching across much of Texas, so fertilizer for next year may not be at the top of anyone’s list right now. But for organic farmers, I think it deserves some attention before we get much farther into fall.
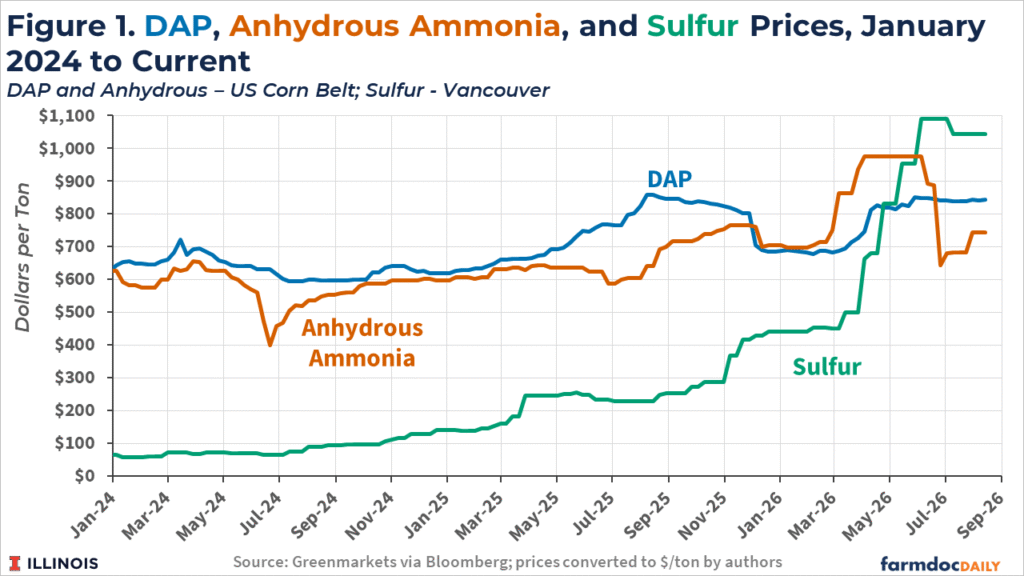
Commercial fertilizer prices have generally moved higher during 2026, particularly for nitrogen and phosphorus fertilizers. Current fertilizer market reports are also raising concerns about higher fertility costs for the 2027 crop. University of Illinois farm economists recently noted that nitrogen and phosphorus fertilizer prices are higher going into fall and that farmers are already beginning to make fertilizer purchasing decisions for 2027.1
Farmdoc Daily graph showing DAP, anhydrous ammonia, and sulfur prices from January 2024 through September 2026. DAP and anhydrous ammonia prices increased during 2025 and remained elevated in 2026, while sulfur prices rose especially sharply, climbing from below $300 per ton in early 2025 to more than $1,000 per ton in mid-2026. Source: GreenMarkets via Bloomberg; graph by farmdoc Daily, University of Illinois.
Why should an organic farmer care about the price of urea, DAP, or anhydrous ammonia when those products are not part of an organic fertility program?
Because conventional fertilizer prices help determine the value of manure, compost, poultry litter, and other nutrient sources that organic farmers depend upon.
When commercial nitrogen, phosphorus, and potassium become more expensive, manure and compost become more valuable to conventional farmers as alternative fertilizer sources. A farmer who may not normally consider poultry litter or manure can quickly become interested when the nutrients in that material cost substantially less than purchasing the same nutrients in a fertilizer blend.
That means organic farmers may face more competition for the same products they routinely use.
In January, I normally update my “What Is the True Cost of Compost or Manure?” calculations using current fertilizer and manure prices. The purpose is to compare the nutrient value of manure or compost with the cost of replacing those same nutrients using conventional fertilizer.
Those January 2026 calculations already showed why this matters. One poultry manure source priced at about $43 per ton contained nutrients with a calculated fertilizer replacement value of more than $100 per ton before considering hauling and application costs. As conventional fertilizer prices rise, that replacement value rises as well—even though the manure itself has not changed.
This does not mean every organic producer should rush out and buy whatever manure or compost is available. Nutrient analysis still matters. Transportation matters. Application cost matters. Phosphorus loading matters. And organic producers still need to verify that any material they use complies with their Organic System Plan and certification requirements.
But I do think it means we should start asking questions now.
If you know you will need manure, compost, poultry litter, pelleted fertilizer, or another organic fertility product for the 2027 crop, contact your supplier. Ask what they expect to have available. Ask about price. Get a current nutrient analysis. Calculate how many tons you are likely to need. And perhaps most importantly, find out whether that material can be reserved or contracted ahead of time.
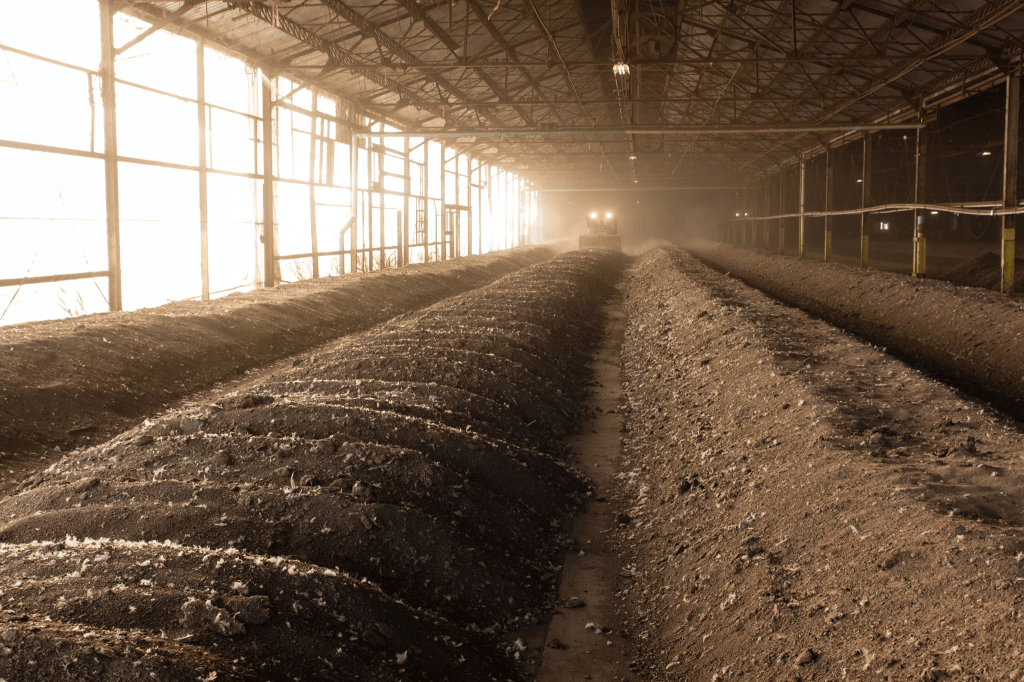
Rows of composting poultry litter are turned and managed inside a covered composting facility. The windrows help promote aeration and controlled decomposition, producing a more uniform organic fertilizer material for agricultural use.Photo courtesy of ViaTrac Fertilizer, used from the ViaTrac Fertilizer photo gallery: https://viatracfertilizer.com/gallery/
Waiting until January or February may mean entering the market after many conventional farmers have already begun looking for the same nutrients.
There is still considerable uncertainty in fertilizer markets, and I am not trying to predict exactly what fertilizer will cost next spring. Retail prices can lag wholesale markets because of inventories, transportation, and purchasing decisions made months earlier.
For an organic farmer, the important message is simpler:
Do not wait for fertilizer prices to tell you that manure and compost have become valuable. Someone else may have already figured that out.
I will update the full compost and manure cost comparison again in January as I normally do. But between now and then, it may be worth making a few phone calls and making sure your 2027 fertility supply is still going to be there when you need it.
Paulson, N., G. Schnitkey, C. Zulauf, and A. Dhakal. 2026. “Sulfur and Increasing Phosphate Fertilizer Prices.”farmdoc daily 16(152), Department of Agricultural and Consumer Economics, University of Illinois at Urbana-Champaign, August 25, 2026. ↩︎
U.S. organic cotton production held nearly steady in 2025, while stronger Pima opportunities, lighter demand and global competition are beginning to reshape planting decisions for Texas growers.
Production Holds Steady, but the Market Is Shifting
USDA Agricultural Marketing Service has released its 2026 Organic Cotton Market Summary for the 2025 marketing year, and this year’s report tells a somewhat different story than the one we saw a year ago.
Last year’s report showed a substantial rebound in U.S. organic cotton production, with the 2024 crop reaching 56,717 bales, an increase of more than 17,000 bales from 2023.
For 2025, production increased again—but only slightly.
Organic Cotton Production
U.S. production of organic Upland and American Pima cotton totaled 57,802 bales in 2025, an increase of just 1,085 bales, or about 1.9%, from 2024.
An additional 1,015 bales of transitional cotton were reported, down from 1,201 bales the previous year.
Texas continues to lead the nation in organic cotton planting and production, with additional organic acreage in Arizona, California and New Mexico.
The production numbers are important because they suggest that the large rebound we saw in 2024 did not continue at the same pace. Organic cotton production essentially leveled off in 2025.
Organic Cottonseed Remains Valuable
Organic cottonseed continues to be an important part of the value of the crop.
USDA reported organic cottonseed prices ranging from $385 to $660 per ton, compared with only $215 to $350 per ton for conventional cottonseed. Cottonseed yields ranged from 500 to 897 pounds of seed per bale of lint.
Most organic cottonseed continues to move into the organic dairy industry, with smaller amounts retained for oil production and livestock feed.
That relationship between Texas organic cotton and organic dairy remains important. Cotton is not simply producing lint for the textile market; the seed is also supplying a valuable certified organic livestock feed ingredient.
The 2026 Crop May Be Telling Us More About the Market
For me, the most interesting part of this year’s report may actually be USDA’s comments about the 2026 crop outlook.
Timely August rainfall helped relieve heat stress, although some fields were lost to hail and excessive heat. USDA also reports that overall organic cotton acreage was lower, in part because of crop rotations.
USDA also reports that organic cotton demand remains “light amid strong global competition.”
Those two statements probably tell us more about the current organic cotton market than the modest increase in 2025 production.
Growers respond to markets. If contracts and premiums are stronger for organic Pima cotton than for organic Upland cotton, acreage will naturally begin moving in that direction where production conditions allow it.
At the same time, continued global competition is putting pressure on the U.S. organic cotton market.
My Take
A year ago, the big story was the recovery in organic cotton production. This year, I think the story is stability combined with change underneath the numbers.
Production increased from 56,717 to 57,802 bales, but that is essentially a flat year compared with the dramatic increase we saw in 2024. Meanwhile, transitional production declined, organic Upland acreage is reportedly falling, growers are responding to better Pima opportunities, and USDA continues to describe demand as light.
For Texas organic cotton growers, that makes contracts and market signals increasingly important. Producing organic cotton is expensive, especially when we consider weed control, rotations, fertility, seed availability and the additional management required under organic production. Acreage is unlikely to expand simply because organic cotton can be grown. There has to be a market willing to pay for it.
Texas remains the center of U.S. organic cotton production, but where that production goes—Upland versus Pima and perhaps even cotton versus other rotational crops—will increasingly depend on those market opportunities.
New Deal, Texas | Registration begins at 9:30 a.m. | No registration fee
One of the continuing challenges for organic crop producers is finding seed varieties developed for the conditions in which we actually farm. This is especially true in the Texas High Plains, where crops must perform under heat, limited rainfall, declining irrigation capacity, organic fertility programs, and significant insect and disease pressure.
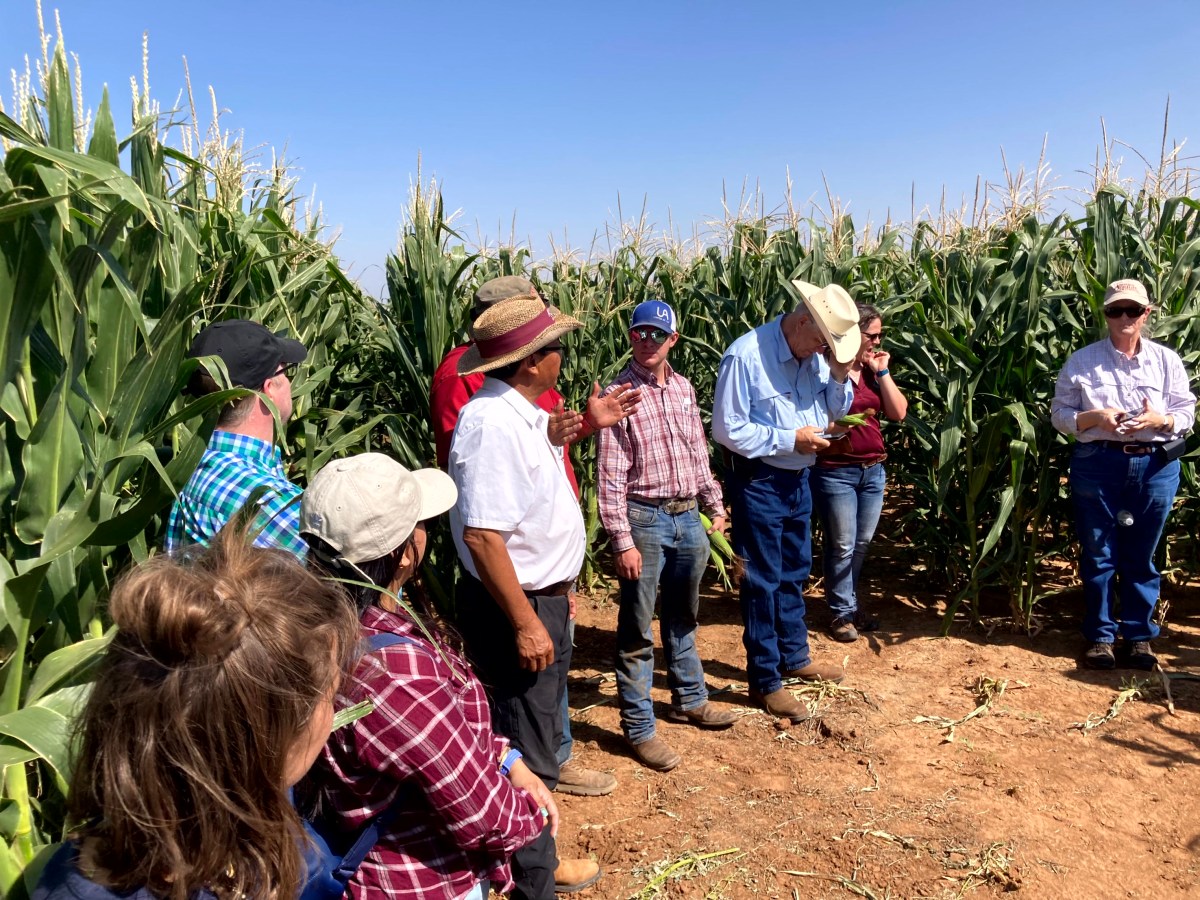
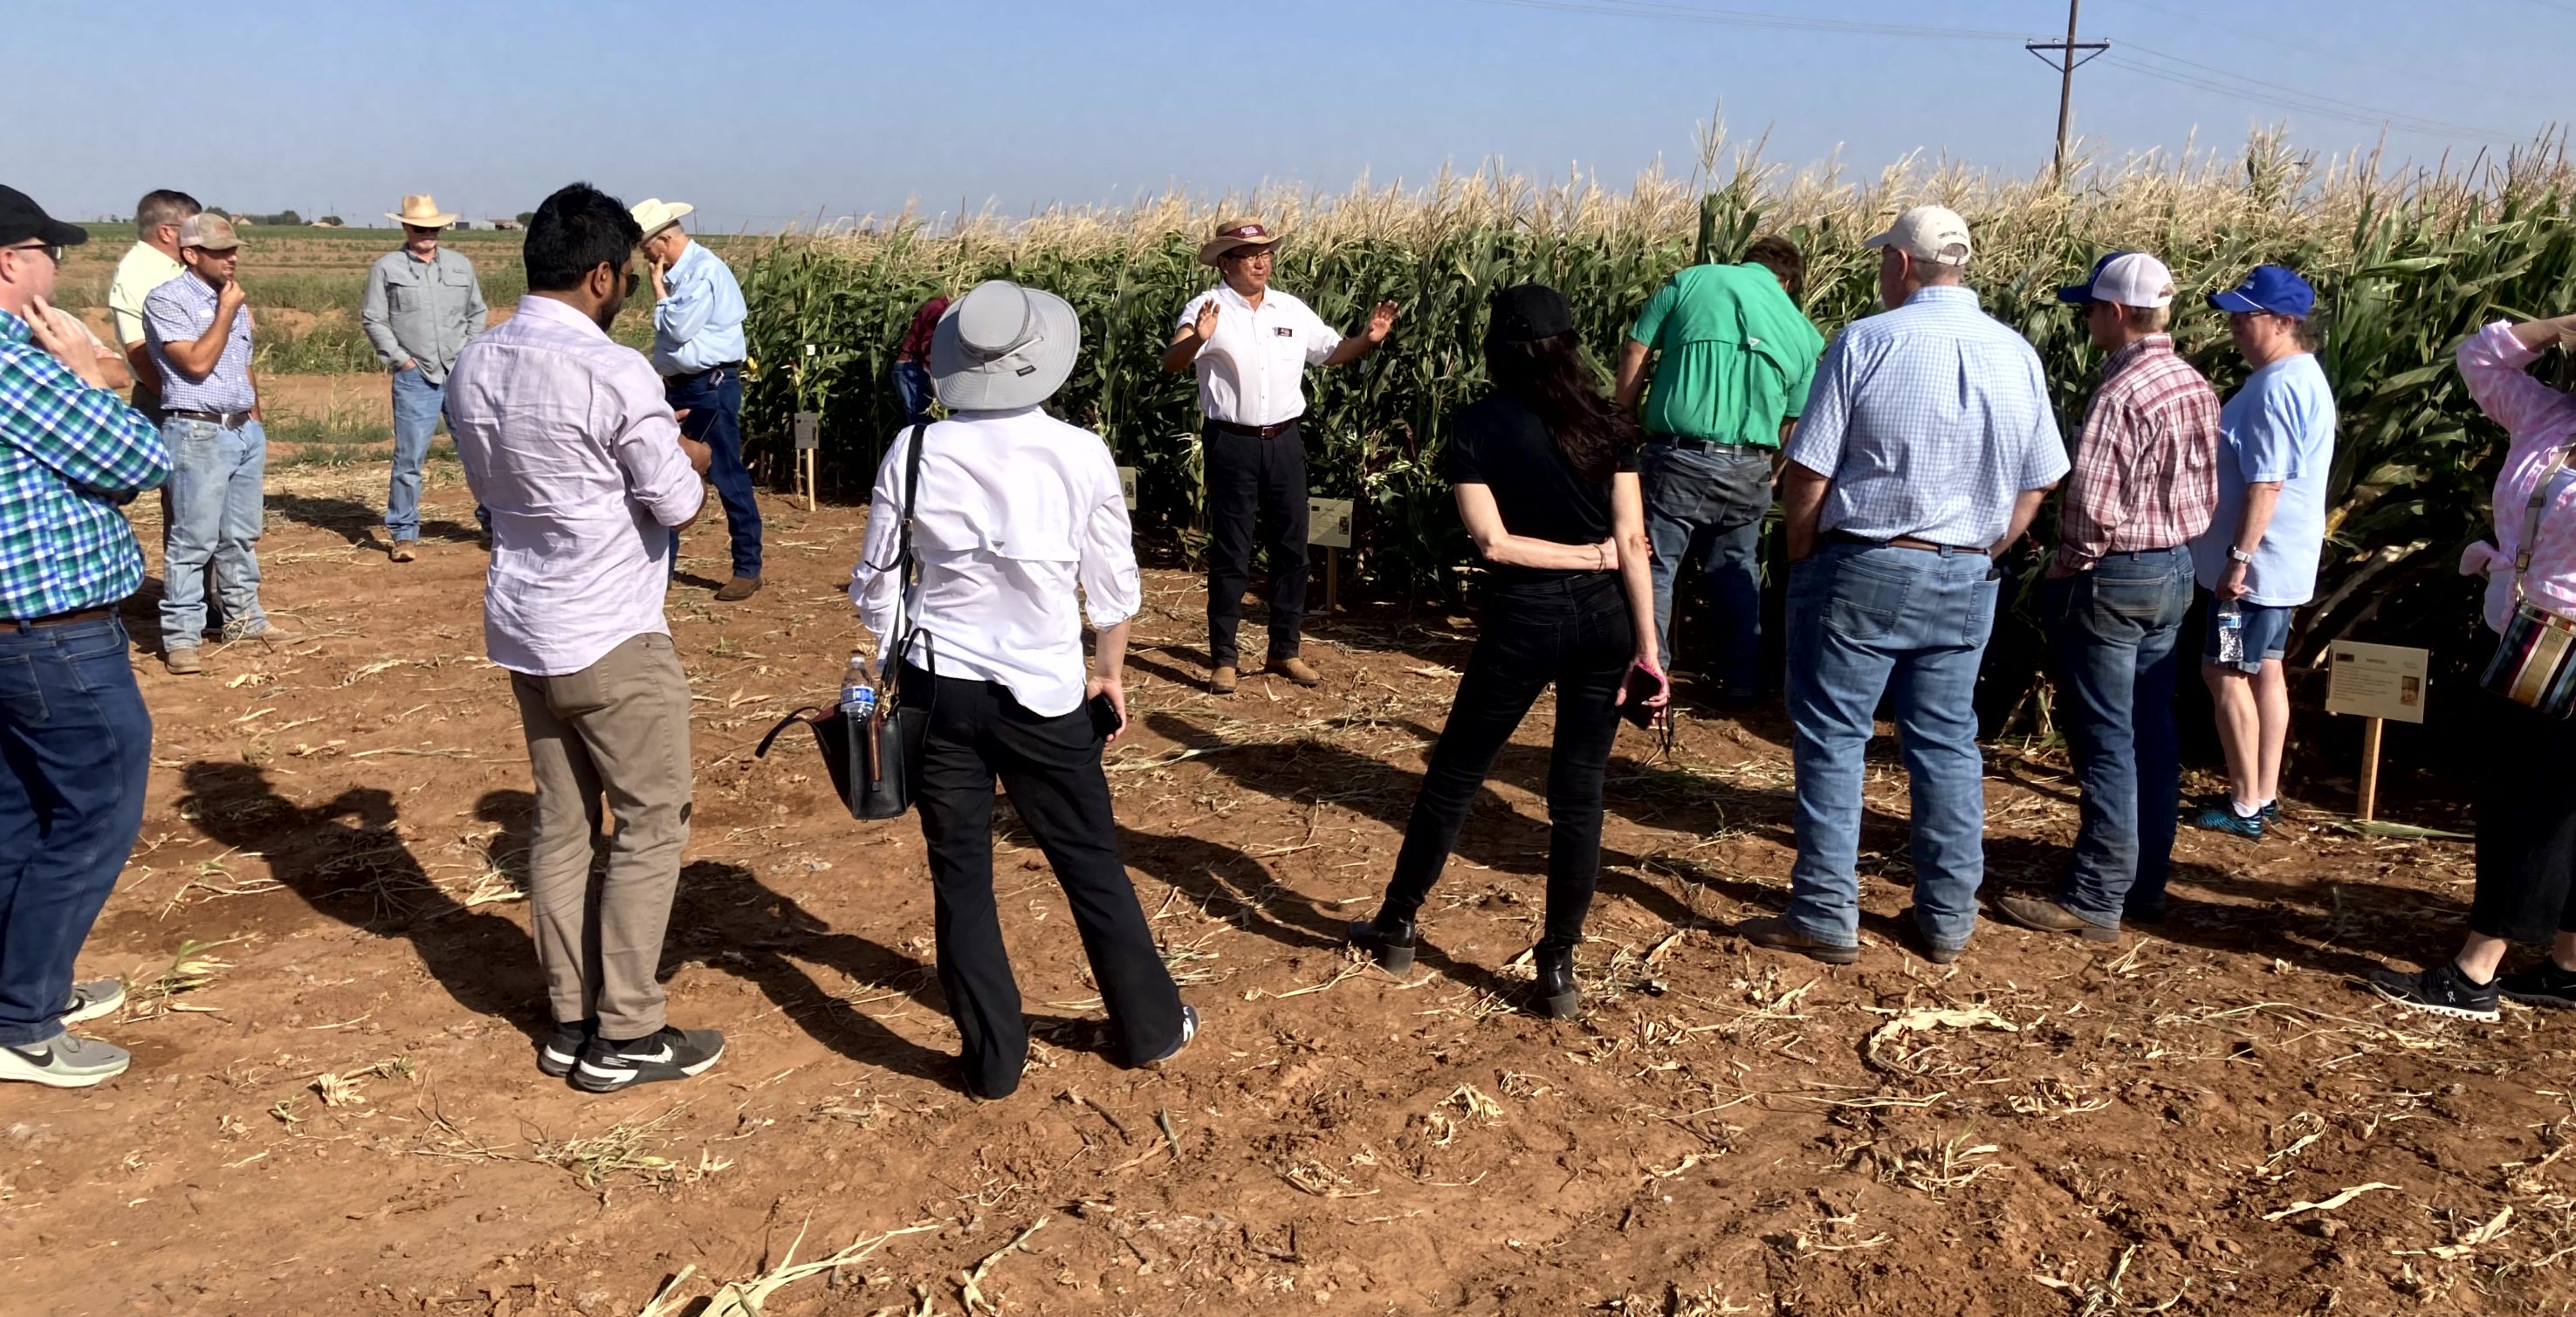
On Thursday, September 3, we will hold an Organic Variety Production Tour in the New Deal–Lubbock area to look at efforts underway to address that problem. This tour is built around a Southern SARE Producer Grant led by Seth Fortenberry of New Deal Grain that is helping develop local capacity to produce and supply non-GMO hybrid corn seed for organic and water-limited cropping systems.
Seth farms organic crops in the Texas High Plains and operates New Deal Grain, an organic grain and seed business. One of the problems he and other organic growers continue to face is the limited availability of non-GMO corn hybrids adapted to the hot, dry conditions of our region. Most corn seed production and much of the breeding work supplying non-GMO hybrids has historically been centered in the Midwest. The goal of this project is to begin closing that gap by taking regionally adapted genetics, producing the seed locally, and ultimately making those hybrids available to organic farmers.
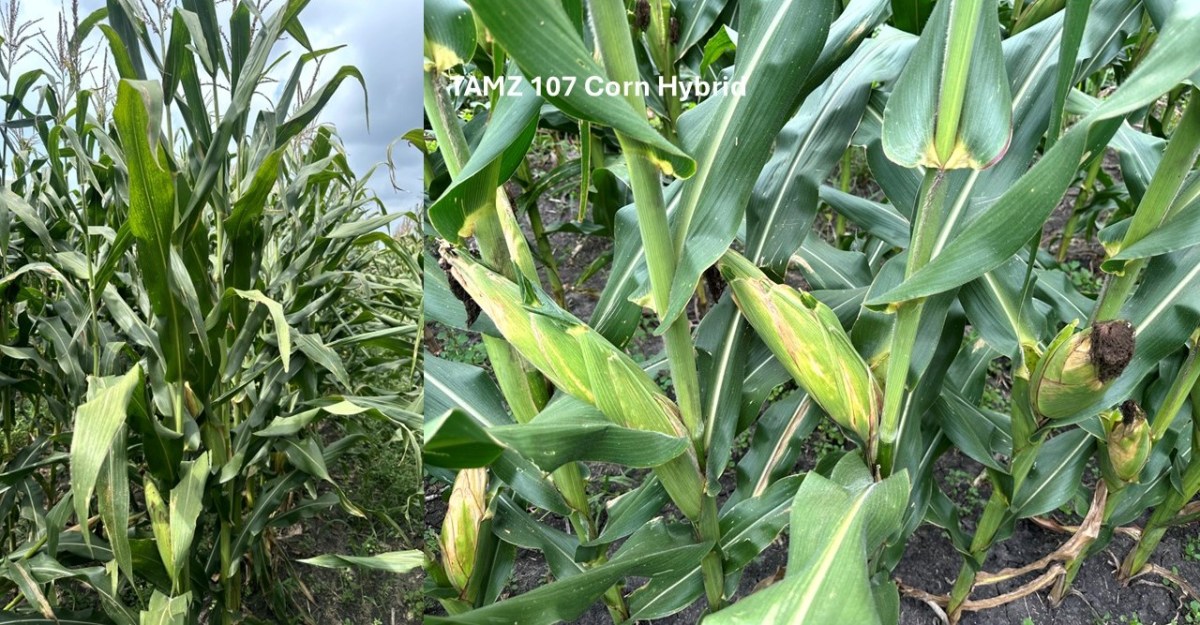
New Deal Grain has licensed TAMZ106B and TAMZ107, two non-GMO corn hybrids developed through the Texas A&M AgriLife corn breeding program. The SARE project is helping Seth build the specialized knowledge and infrastructure needed to increase parent seed, produce hybrid seed, maintain genetic purity, process and condition the harvested seed, and move that seed into commercial production. The project also includes testing these hybrids on certified organic farms and comparing their performance under actual production conditions.
The September tour will use that corn seed project as a starting point, but the discussion will be broader. We will look at corn, sorghum, cowpea and guar plots and talk about what characteristics we need when selecting and developing varieties for organic agriculture. That may include yield, drought and heat tolerance, disease and insect resistance, weed competitiveness, forage quality, food quality, seed production characteristics, and opportunities for alternative markets.
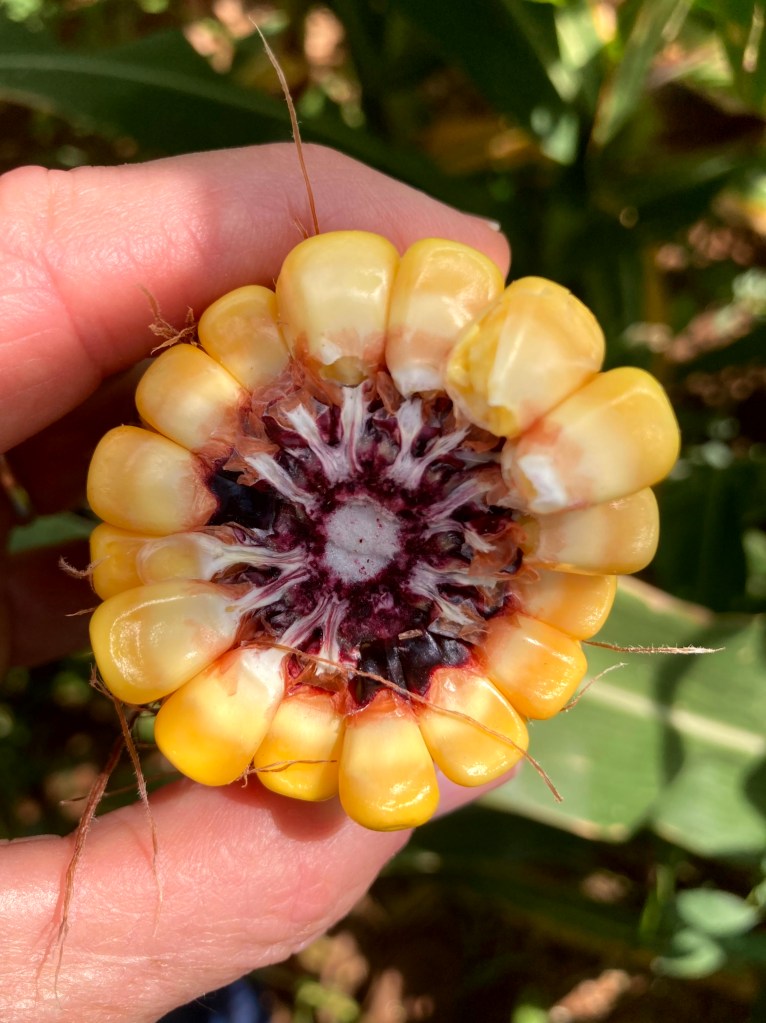
At the Texas Tech corn plots, we will discuss corn breeding, promising crosses, commercial possibilities, and high-anthocyanin or High-A corn being developed for specialty food and health-oriented markets. We will then move to cowpea and guar plots to discuss their potential as cover crops, forage crops, protein crops, and alternative cash crops. The final field discussion will focus on organic sorghum, including variety needs, seed availability, and where we see opportunities for the organic sorghum industry.
This is really a tour about connecting plant breeding, seed production, and farmer needs. Developing a good variety is only the first step. Farmers also need enough high-quality seed, produced and conditioned correctly, at a price and quantity that allows them to actually plant it. Building that connection from the breeder’s plot to the farmer’s planter is one of the important long-term goals of this work.
9:30–10:00 a.m. – Registration, Introductions and Tour Overview at New Deal Grain – Bob Whitney, Extension Organic Specialist and Seth Fortenberry, New Deal Grain
10:15 a.m. – Corn Breeding and Variety Development Overview of the corn breeding program, varieties and crosses, potential industry uses, and High-A corn. Andrew Sellers, Texas A&M AgriLife Research Corn Breeding Technician and Bob Whitney
10:45 a.m. – Depart for Sorghum, Cowpea and Guar Plots
10:55 a.m. – Field Overview – Seth Fortenberry
11:00 a.m. – Organic Cowpea and Guar Discussion of the plots and their potential as cover crops, protein crops, forage crops, and alternative crops for organic production – Dr. Waltram Ravelombola, Assistant Professor, Organic & Specialty Crop Breeding
11:25 a.m. – Organic Sorghum Sorghum plot discussion, organic sorghum production and variety development, seed needs, and the future of organic sorghum – Dr. Bill Rooney, Professor, Sorghum Crop Breeder and Nick Porter, Senior Research Associate, Sorghum Breeding
12:00 noon – Depart for Lunch at the Texas A&M AgriLife Research and Extension Center at Lubbock Lunch provided by Orlando’s
12:45 p.m. – Wrap-Up
Registration
There is no cost to attend the tour or lunch, but we need an accurate meal count.
Please contact Bob Whitney at 979-571-2086 to register.
Registration begins at 9:30 a.m. at New Deal Grain in New Deal, Texas, and we will leave for the field tour promptly at 10:00 a.m.
A wet 2026 Texas corn trial highlighted TAMZ107’s strong ear-rot resistance, showing how years of public plant breeding can deliver disease protection directly through the seed.
Sometimes two ears of corn can tell an important plant-breeding story.
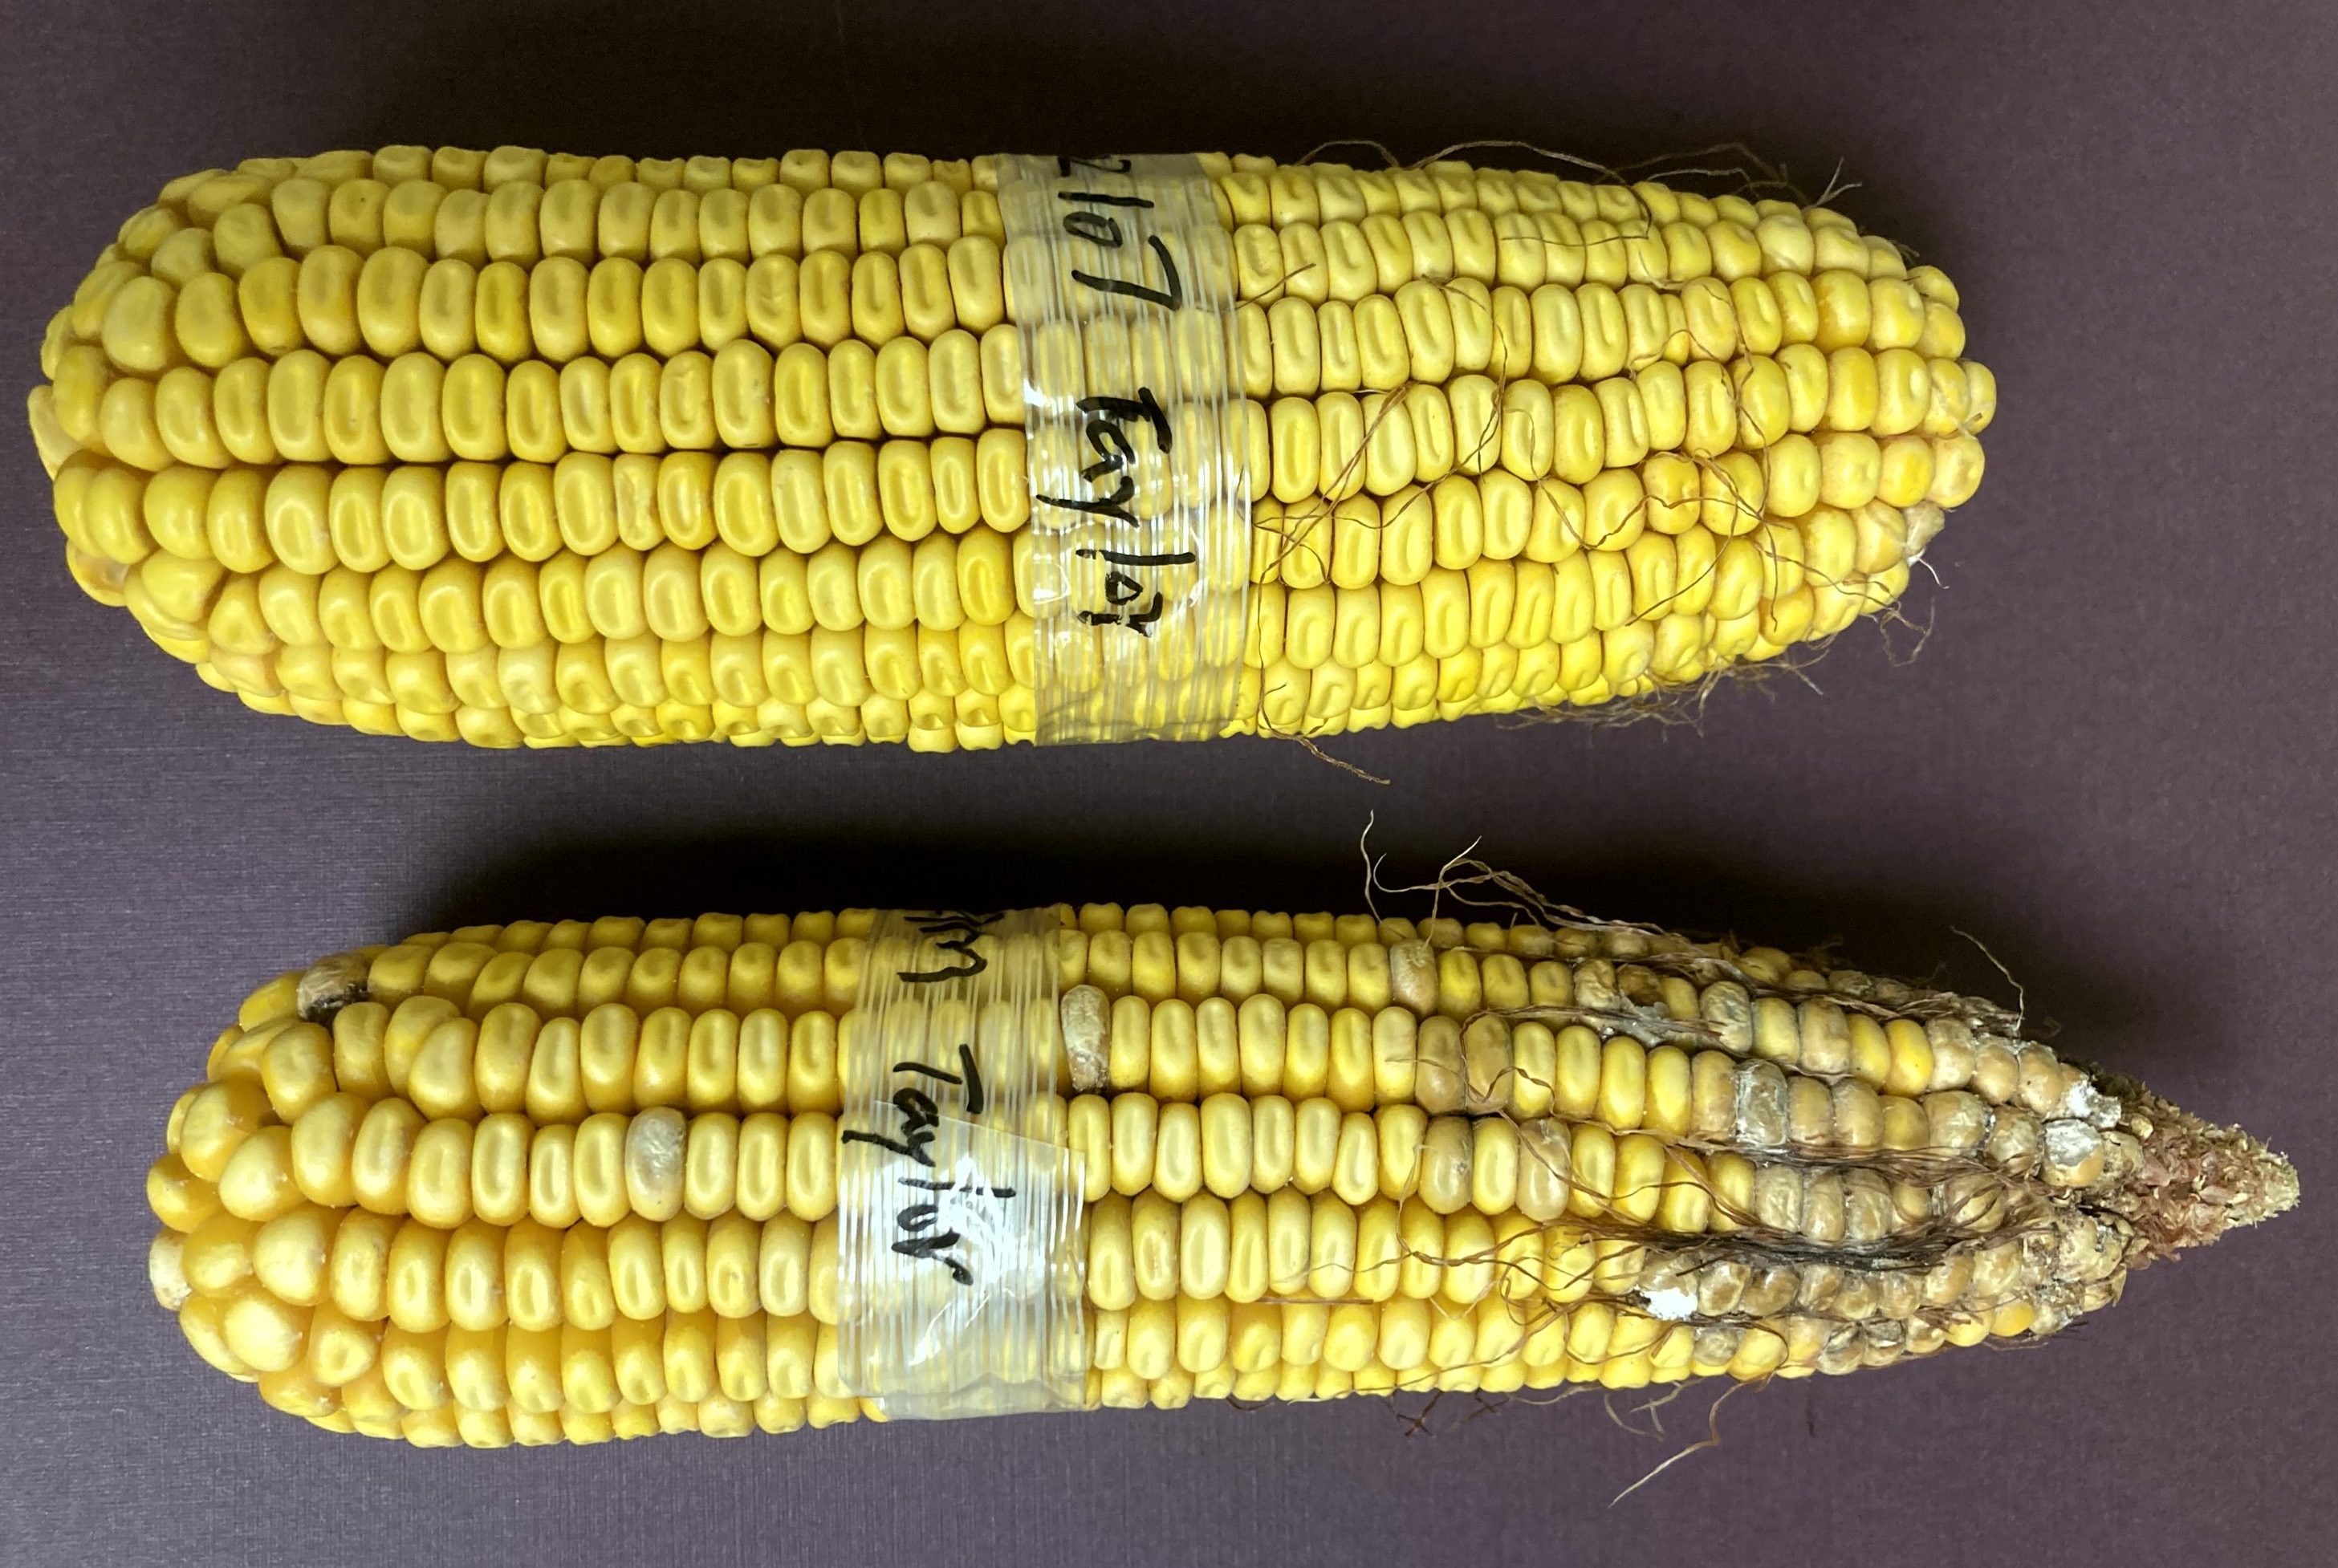
Ears from the 2026 Taylor, Texas, corn hybrid trial. TAMZ107 (top) remained free of visible ear-rot symptoms, while an unnamed commercial hybrid (bottom) showed severe ear-rot damage.
Both ears pictured came from a 2026 corn hybrid trial near Taylor, Texas—one location in our multilocation testing program. The ear on top is TAMZ107, developed by Dr. Wenwei Xu, Texas A&M AgriLife Research corn breeder at Lubbock. The ear on bottom is an unnamed commercial hybrid.
Frequent rainfall and humid conditions during the 2026 growing season have favored corn ear rots across parts of Texas. The commercial ear shows severe ear-rot symptoms, with Fusarium among the predominant ear-rot pathogens observed this season. All commercial hybrids in this trial showed some ear-rot damage, while the TAMZ hybrids remained free of visible symptoms.
The importance of this comparison is not the identity of the commercial company. It is the value of years of public plant breeding. Dr. Xu selected resistant inbred parents and combined them to produce TAMZ hybrids adapted to Texas conditions. TAMZ107 has been tested for several years and is now ready for release and fits an organic program because it is GMO free and adapted to organic conditions.
Genetic resistance is especially valuable for organic farmers because it arrives in the seed. The plant begins the season with its own protection rather than depending on a treatment after disease develops. Resistant hybrids can also benefit any farmer facing difficult weather and disease pressure.
See the TAMZ Hybrids in the Field
The TAMZ hybrids will be featured during the Field to Fiesta Corn Tour on Wednesday, August 12, beginning at 9 a.m. at the Halfway Research Center in Halfway, Texas. The tour will include the research center and nearby farm fields, followed by a sponsored lunch.
Topics will include heat during pollination, corn borers and earworms, drought tolerance, ear rots and herbicide drift. For attendance information, contact Extension Agronomist Kristie Keys at kristie.keys@ag.tamu.edu. View the program announcement.
Organic markets are increasingly shaped by quality, traceability, buyer relationships and trust. This update looks at 2026 trends in organic wheat, corn, dairy and soybeans, along with stronger USDA oversight of imported organic products and what these changes may mean for Texas producers. Texas A&M AgriLife Organic
Organic Agriculture as a Long-Term Strategy
Organic agriculture is increasingly revealing itself as more than simply a production system built around prohibited substances. Over the long term, it may be better understood as a biological and economic strategy centered on trust, resilience, traceability, and system function. While conventional agriculture often optimized around maximum efficiency, scale, and external inputs, organic agriculture has gradually emphasized relationships between soil biology, nutrient cycling, biodiversity, food quality, and consumer confidence. The USDA National Organic Program helped create a framework where consumers can trust production methods they cannot personally observe, making organic agriculture as much a transparency system as a farming system. At the same time, many long-term organic farmers increasingly report that mature organic systems (greater than 5-7 years) often become less dependent on purchased inputs as soil health, rotations, and biological regulation improve over time.
I hear often from farmers, bakers, dairy processors, and food manufacturers who frequently report differences in flavor, functionality, storage, processing quality, and handling characteristics that go beyond simple yield measurements. Meanwhile, rising transportation costs, supply-chain complexity, and consumer interest in traceability may and do, increasingly favor organic systems. Also, we are seeing technologies such as digital traceability, AI-driven compliance systems, and integrated recordkeeping beginning to reduce some of the traditional burdens associated with organic certification.
These broader trends are also becoming increasingly visible within organic grain and dairy markets themselves, where pricing is often shaped less by simple commodity production and more by quality, traceability, transportation, end use, and long-term supply relationships. Current (Jan. to May 2026) USDA AMS reports and organic market activity continue to show that organic agriculture operates through highly differentiated markets where buyer confidence, dependable supply, and product identity can significantly influence value.
Organic Market Report for Texas Organic Farmers
Organic markets continue to show strong differentiation by quality, delivery structure, end use, and contract type rather than functioning as simple commodity markets. Across grains and dairy, USDA AMS reports continue to show active forward contracting, regional price variation, and premiums tied to quality, storage, transportation, and dependable supply relationships. While organic market reporting remains in “short supply” in some Southern regions, including Texas, the overall market signals suggest that buyers continue working to secure reliable supplies of organic feed grains, food-grade products, and dairy inputs well ahead of delivery.
Organic Wheat
Organic wheat prices remain highly differentiated by class, protein, buyer type, delivery terms, and contract structure. In recent AMS reports, Soft Red Winter values often fall in the high single digits to low teens, while Hard Red Spring commands a stronger premium, with some flour-mill forward contracts reaching $20/bu. The main takeaway is that organic wheat is priced less as a generic commodity and more as a set of niche markets defined by end use, quality, freight terms, and whether the transaction is spot, bid, or forward contracted.
For Texas organic wheat farmers, this means harvest is also a marketing decision. Growers who can protect test weight, maintain protein, and keep grain clean and dry are in the best position to capture milling premiums, while those selling quickly into generic feed or elevator channels may leave money on the table. Before cutting, it is worth comparing buyers, delivery terms, and contract options, because in this market the details can matter as much as the wheat itself.
Organic Corn
Organic corn markets continue to show relatively strong and stable pricing compared to many other organic commodities, with much of the AMS-reported activity clustering around the mid-$10 per bushel range (but I see it steadily increasing). Prices still vary by location, contract structure, and whether the grain is old crop or new crop, but the overall pattern suggests a market supported by steady feed demand, active forward contracting, and ongoing regional supply shortages. Unlike organic wheat, where protein and milling quality create wider price separation, organic corn remains heavily influenced by livestock feed demand, freight costs, and regional availability.
For Texas organic corn growers, the message is to stay flexible and market carefully checking regularly on prices. Producers who can store grain, preserve quality, and deliver into specialty feed, dairy, poultry, or food-grade channels may be able to capture better returns than those forced to sell at harvest. Transportation costs and local buyer demand can make a meaningful difference, particularly in regions where organic feed supplies remain limited. Forward contracts (some but not all!) also remain important because they help secure long-term supply relationships and reduce risk in a market that continues rewarding dependable volume and consistent quality.
Organic Dairy
The USDA Organic Dairy Market News Report for May 4–15 provides a snapshot of current organic dairy market conditions rather than a policy or technical standards document. The report shows that organic milk demand remained strong during spring 2026, with U.S. sales of total organic milk products up 5.6 percent for March and organic whole milk sales also showing strong year-over-year growth. Retail organic dairy products, especially milk and yogurt, continue maintaining noticeable price premiums, reflecting continued consumer demand for organic dairy products and broader interest in food products associated with transparency, animal welfare, and ingredient sourcing.
The report also demonstrates how closely the organic dairy sector remains tied to feed markets and broader supply conditions. Organic grain and feed markets remain active, with some forward contracts extending into 2027, indicating that buyers continue working to secure future supply. For producers, the overall signal is that organic dairy demand and premium pricing remain solid, but feed costs, export movement, and retail advertising trends continue shaping a competitive market that remains sensitive to supply and input conditions.
Organic Soybeans
I know we don’t produce many organic soybeans, but they do indicate some import protein trends. Organic soybean markets continue showing some of the strongest structural support among major organic grain commodities, with pricing being driven largely by protein demand, livestock feed markets, and food-grade specialty channels. Unlike organic wheat, where class and milling quality create major price separation, soybean values appear more closely tied to dependable supply, identity preservation, and end use. AMS-reported activity suggests that forward contracting remains active, indicating that buyers continue working to secure long-term supply in a market where domestic production remains limited and imported soybeans still influence overall availability and pricing.
For Texas organic producers, soybeans provide an important lesson even where acreage remains limited. Organic soybean markets demonstrate how protein quality, cleanliness, storage, and buyer relationships increasingly shape value in organic agriculture. Food-grade and identity-preserved soybeans can carry significant premiums over generic feed channels, reinforcing the idea that organic crops are often marketed less as bulk commodities and more as differentiated products tied to specific supply chains. The continued influence of imported soybeans also highlights the importance of dependable domestic production capable of meeting both feed and food-grade demand.
As Texas organic markets continue developing, similar trends may increasingly influence corn, sorghum, wheat, peanuts, and other crops where end use, traceability, and dependable supply relationships become more important than simple yield alone.
Organic Integrity and Import Oversight Expand Under USDA SOE Rule
The USDA National Organic Program continues expanding oversight of imported organic products through the Strengthening Organic Enforcement (SOE) rule. New Organic Insider reports highlight how USDA is now using import certificate data, shipment tracking, and compliance analytics to identify irregular trade patterns and investigate potential fraud before products reach the marketplace. Several recent investigations involved imported organic products lacking valid import certificates, while another case involving raspberries from Mexico demonstrated how residue testing and traceability systems prevented contaminated products from entering U.S. commerce. The increased emphasis on farm-to-market traceability reflects USDA’s growing focus on maintaining consumer confidence and strengthening enforcement throughout global organic supply chains.
The newly released 2025 organic import data also provide a revealing picture of the modern organic marketplace. Total U.S. organic imports approached $12 billion in 2025 (total organic sales in the US are $76 billion), with Mexico representing more than 20% of total import value. Organic beef, coffee, bananas, blueberries, avocados, olive oil, and processed soybean products ranked among the largest import categories. The data reinforce that organic agriculture has become deeply connected to international supply chains and value-added food manufacturing systems rather than operating solely as a domestic farm commodity market.
For U.S. organic producers, these trends highlight both continued strong consumer demand for organic products and the increasing importance of traceability, market relationships, and maintaining trust in the organic label. For Texas organic farmers specifically, future competitiveness may depend less on maximizing volume alone and more on building dependable supply relationships, preserving quality, improving traceability, and positioning farms within regional food systems that value identity preservation, biological function, and long-term resilience.
Sources and Market References
This market analysis and commentary were developed using information from the following USDA and industry reports:
USDA AMS National Organic Feed Grain and Feedstuffs Report, January 1, 2026 – April 27, 2026
Additional market interpretation and analysis were developed through ongoing observations of organic grain, dairy, and specialty crop markets relevant to Texas organic producers.